Close Menu
CEOColumnCEOColumn
    What's Hot

    The Strategic Exit: Planning Your E-commerce Future

    October 13, 2026

    How National Advocates Help Veterans Appeal Wrongful Denials

    October 13, 2026

    How to Budget for Digital Marketing When Starting a Business

    October 13, 2026
    Facebook X (Twitter) Instagram
    Facebook X (Twitter) Instagram
    CEOColumnCEOColumn
    Subscribe
    • Home
    • News
    • BLOGS
      1. Health
      2. Lifestyle
      3. Travel
      4. Tips & guide
      5. View All

      Why Is My Hair Thinning? 7 Common Causes and What You Can Do About Them

      October 13, 2026

      How Fermented Cod Liver Oil Supports Immunity, Heart Health, And Mood

      October 9, 2026

      Are Porcelain Veneers Worth It? Questions to Ask First

      October 9, 2026

      How Do Online Dental CE Courses Help When Clinical Knowledge Needs a Refresh?

      October 9, 2026

      How to Plan a Proposal Around Your Partner’s Style

      October 8, 2026

      Best Shampoo for Dandruff: Top Picks for a Healthy Scalp

      October 5, 2026

      Orient Watches Explained: Features, Functions and Design Details

      September 24, 2026

      How to Choose Red Wedding Flowers That Actually Match Your Venue

      September 19, 2026

      Red Sea Days and Desert Nights in Hurghada

      October 7, 2026

      Luxury Crewed Yacht Charters in Greece: A Complete Guide to Private Yacht Holidays

      October 2, 2026

      Flying from the US to Guadalajara: what to see and do in Mexico’s cultural capital

      September 2, 2026

      Black Friday travel deals: How to plan a trip around the sale window

      September 2, 2026

      Language Barriers While Traveling: What Actually Helps in Real-World Conversations?

      September 29, 2026

      How therapeutic techniques can vary from one practitioner to another

      September 29, 2026

      Turning Anger Into A Boundary Statement

      September 11, 2026

      4 Strategies for Faster Trial Prep Without Loosing Accuracy

      August 27, 2026

      How National Advocates Help Veterans Appeal Wrongful Denials

      October 13, 2026

      How to Budget for Digital Marketing When Starting a Business

      October 13, 2026

      From Supply Chain Leader to Enterprise Leader

      October 13, 2026

      How Growing Life Sciences Companies Can Plan for Regulatory Compliance

      October 12, 2026
    • BUSINESS
      • OFFLINE BUSINESS
      • ONLINE BUSINESS
    • PROFILES
      • ENTREPRENEUR
      • HIGHEST PAID
      • RICHEST
      • WOMEN ENTREPRENEURS
    • Audit
    CEOColumnCEOColumn
    Home»BUSINESS»A Comprehensive Consumer Guide Explaining What is Term Insurance and How to Compare Term Insurance Plans

    A Comprehensive Consumer Guide Explaining What is Term Insurance and How to Compare Term Insurance Plans

    OliviaBy OliviaJune 15, 2026Updated:June 15, 2026No Comments5 Mins Read

    Most people buying term insurance do not fully know what they are buying. They heard it is important, the premium is low, and they signed up. This guide is for people who want to understand what is term insurance before buying and know what to check when comparing plans.

    Table of Contents

    Toggle
    • What Is Term Insurance in Simple Words
    • Who Needs It
    • How Much Cover Should You Buy
    • How Long Should the Term Be
    • How to Compare Term Insurance Plans
      • Claim Settlement Ratio
      • Premium for Your Profile
      • Rider Options
      • Payout Structure
      • Exclusions
      • Maximum Cover Age
    • A Few Things to Check Before You Buy
    • The Longer You Wait, the More It Costs

    What Is Term Insurance in Simple Words

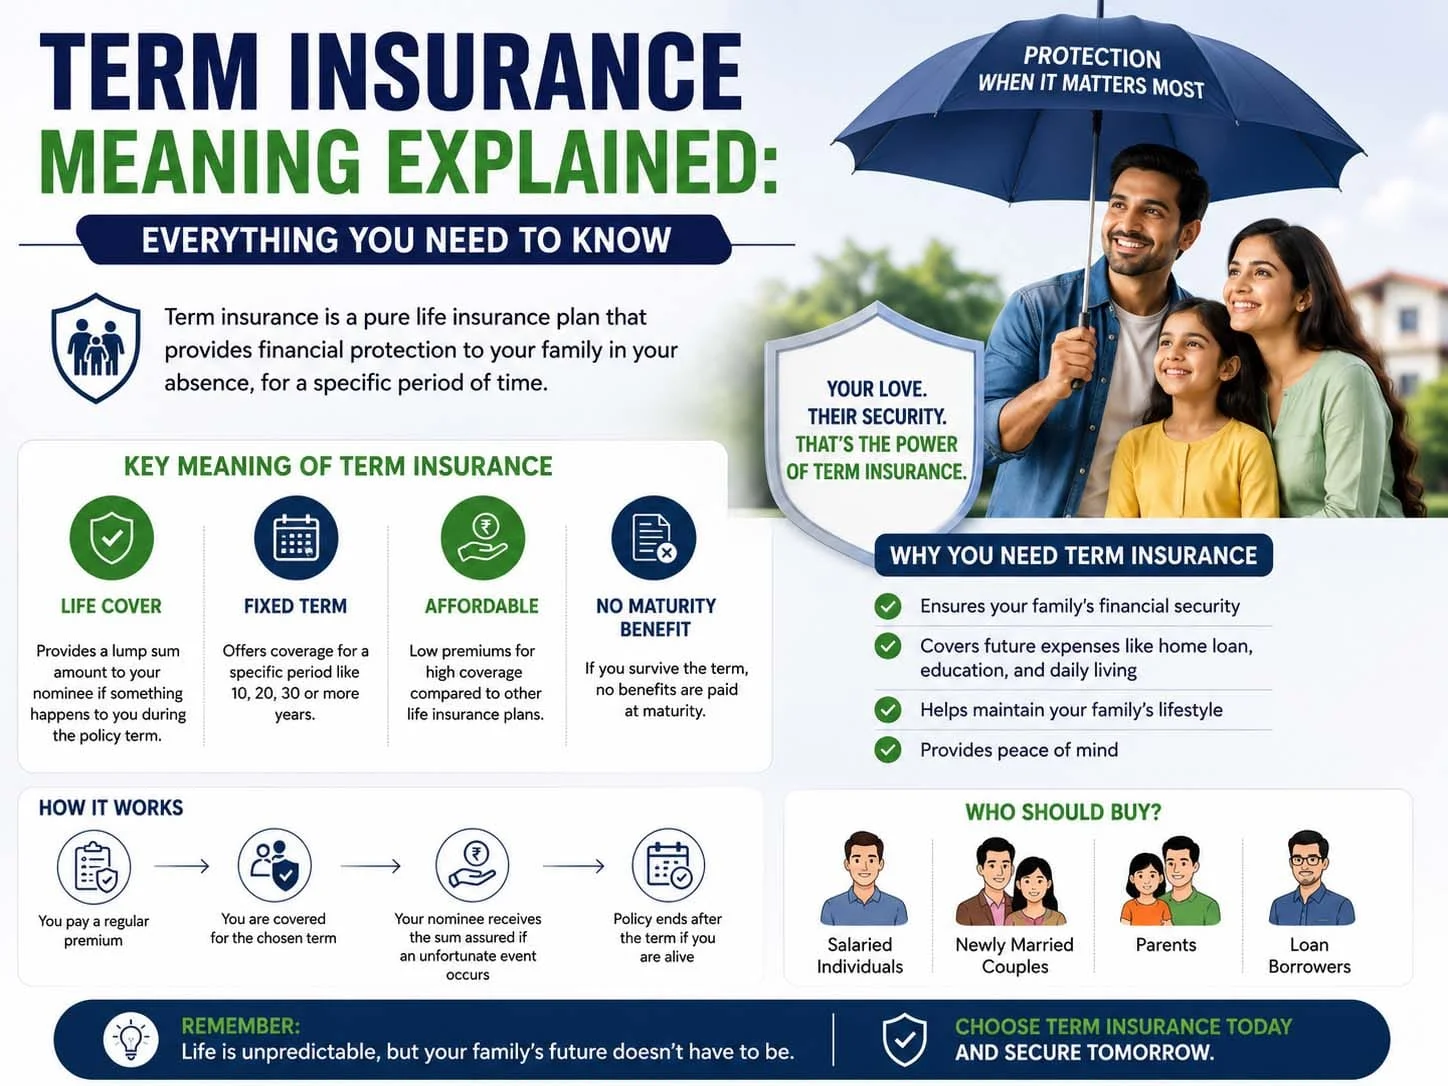
    You pay a premium every year. The insurer covers your life for a fixed number of years. If you die during that period, your family gets a large payout called the sum assured. If you are alive when the policy ends, it is over. No money comes back.

    That is the full product. Nothing hidden.

    People hear “no money back” and think it is a bad deal. It is actually the reason premiums are so affordable. A 30-year-old in decent health can get ₹1 crore of cover for around ₹800 a month. Try getting that in any other life insurance product. You cannot.

    The job of a term plan is not to grow your money. It is to make sure your family does not face a financial crisis if you are not around.

    Who Needs It

    If someone depends on your income, you need it.

    Your spouse, your children, your parents, and anyone whose daily life runs on what you earn. If you are gone, that income stops. But rent, school fees, and loan EMIs still need paying.

    A term plan gives your family a lump sum they can use. That is the only job it does.

    If nobody depends on your income and you have no loans, you can hold off. For everyone else it is not optional.

    How Much Cover Should You Buy

    More than you think. Most people pick ₹50 lakh because it sounds big. For most urban families it lasts about 5 to 6 years at best.

    Multiply your annual income by 15. Add all outstanding loans. That is a rough minimum.

    If you earn ₹7 lakh a year and have ₹25 lakh in loans, you need at least ₹1.3 crore. ₹50 lakh leaves a large gap.

    Premiums do not jump much when you increase cover. Going from ₹50 lakh to ₹1 crore often adds ₹200 to ₹300 a month. Worth it.

    How Long Should the Term Be

    Long enough to cover the years when people depend on you.

    If you are 29 and your youngest child is 2, you realistically need cover till at least your child turns 25 and is earning. That is a 23-year term at minimum. Most people round up to 30 or 35 years to be safe.

    One mistake people make is picking a 20-year term to save on premiums. They end up without coverage in their 50s, which is when health issues start, and income is still needed.

    Go longer. The extra cost per year is small.

    How to Compare Term Insurance Plans

    Once you know what is term insurance and how much you need, the next step is comparing plans. Here is what to check.

    Claim Settlement Ratio

    Look this up first. It tells you how many claims the insurer paid out of every 100 received. Above 95 is fine. Below 90 is a concern.

    A low premium means nothing if the insurer finds reasons to reject claims. Your family will be dealing with this without you. Pick an insurer with a reliable track record.

    Premium for Your Profile

    Premiums differ between insurers for the same person. Get quotes from 4 to 5 companies for the same cover amount and same policy duration. Compare those numbers side by side.

    Make sure you are comparing with the same riders included. A plan that looks cheaper at base may cost more once you add the extras.

    Rider Options

    Riders are add-ons to the base plan. Three are worth knowing.

    A critical illness rider pays you money when you are diagnosed with something serious like cancer or a heart condition. Not at death but at diagnosis. That money helps pay for treatment and covers income loss while you recover.

    Waiver of premium rider means if you become permanently disabled, you stop paying premiums, but the policy stays active. No cover is lost.

    Accidental death rider pays an additional amount to the family if death is caused by an accident.

    Add riders based on what you actually need. Not everything.

    Payout Structure

    Most term insurance plans pay the full amount at once. Some let you split it into a lump sum plus a monthly income. If your family does not know how to manage a large one-time amount, the monthly income option is worth considering.

    Exclusions

    Every policy has a section listing what it will not cover. Read it. Common exclusions are suicide in the first policy year, health conditions that were not disclosed at the time of buying, and deaths from certain dangerous activities. These are not buried or complicated. Just read that section once.

    Maximum Cover Age

    Some plans stop covering you at 65 or 70. Others go till 85. If you want to cover later in life, check the upper age limit before you decide.

    A Few Things to Check Before You Buy

    Is the claim settlement ratio above 95? Is the premium affordable for the full term, not just right now? Is the cover amount actually enough? Have you read the exclusions? Does the plan offer the riders you want?

    Those five will quickly filter out the bad ones.

    The Longer You Wait, the More It Costs

    Every year of delay means a higher premium. A 25-year-old pays noticeably less than a 30-year-old. A 30-year-old pays noticeably less than a 35-year-old.

    Health issues that show up later in life also affect premiums. Some conditions push them up sharply. Others make you ineligible.

    Comparing term insurance plans early and picking one locks in the lowest rate for the full policy duration.


    Share. Facebook Twitter Pinterest LinkedIn Tumblr Telegram Email
    Previous ArticleThe Hidden Cost of Poor Team Management
    Next Article The Hidden Technology Challenges International Businesses Face in Japan
    Olivia

    Olivia is a contributing writer at CEOColumn.com, where she explores leadership strategies, business innovation, and entrepreneurial insights shaping today’s corporate world. With a background in business journalism and a passion for executive storytelling, Olivia delivers sharp, thought-provoking content that inspires CEOs, founders, and aspiring leaders alike. When she’s not writing, Olivia enjoys analyzing emerging business trends and mentoring young professionals in the startup ecosystem.

    Related Posts

    How the Kupu178 Official Website Protects User Data and Payment Privacy

    October 13, 2026

    12 Best AEO Tools in 2026: Answer Engine Optimization Platforms Compared

    October 12, 2026

    “Insurance Policy: Types, Benefits, Features and How to Choose One

    October 12, 2026
    Add A Comment
    Leave A Reply Cancel Reply

    You must be logged in to post a comment.

    Latest Posts

    The Strategic Exit: Planning Your E-commerce Future

    October 13, 2026

    How National Advocates Help Veterans Appeal Wrongful Denials

    October 13, 2026

    How to Budget for Digital Marketing When Starting a Business

    October 13, 2026

    How the Kupu178 Official Website Protects User Data and Payment Privacy

    October 13, 2026

    From Supply Chain Leader to Enterprise Leader

    October 13, 2026

    Why Is My Hair Thinning? 7 Common Causes and What You Can Do About Them

    October 13, 2026

    How Business Lending Is Evolving to Meet the Needs of Modern Companies

    October 13, 2026

    Executive Mobility in the UAE: Why Business Travelers Choose Rental Cars

    October 13, 2026

    How Growing Life Sciences Companies Can Plan for Regulatory Compliance

    October 12, 2026

    12 Best AEO Tools in 2026: Answer Engine Optimization Platforms Compared

    October 12, 2026
    Recent Posts
    • The Strategic Exit: Planning Your E-commerce Future October 13, 2026
    • How National Advocates Help Veterans Appeal Wrongful Denials October 13, 2026
    • How to Budget for Digital Marketing When Starting a Business October 13, 2026
    • How the Kupu178 Official Website Protects User Data and Payment Privacy October 13, 2026
    • From Supply Chain Leader to Enterprise Leader October 13, 2026

    Your source for the serious news. CEO Column - We Talk Money, Business & Entrepreneurship. Visit our main page for more demos.

    We're social. Connect with us:
    |
    Email: Support@gposting.com

    Facebook X (Twitter) Instagram Pinterest LinkedIn WhatsApp
    Top Insights

    The Strategic Exit: Planning Your E-commerce Future

    October 13, 2026

    How National Advocates Help Veterans Appeal Wrongful Denials

    October 13, 2026

    How to Budget for Digital Marketing When Starting a Business

    October 13, 2026
    © Copyright 2025, All Rights Reserved
    • Home
    • Pricacy Policy
    • Contact Us

    Type above and press Enter to search. Press Esc to cancel.