Close Menu
CEOColumnCEOColumn
    What's Hot

    How Pest Control In Meridian Solves Seasonal Insect Infestations

    October 25, 2026

    From Estimate to Payment: How Small Construction Firms Can Close the Cash Gap

    October 24, 2026

    Why Auckland Households Are Rethinking How They Move House These Days

    October 24, 2026
    Facebook X (Twitter) Instagram
    Facebook X (Twitter) Instagram
    CEOColumnCEOColumn
    Subscribe
    • Home
    • News
    • BLOGS
      1. Health
      2. Lifestyle
      3. Travel
      4. Tips & guide
      5. View All

      Healthy Habits for Feeling More Relaxed and Centered

      October 23, 2026

      ModafinilUSA Review: What Sets This Modafinil Vendor Apart in the USA Market

      October 23, 2026

      Designing a Distinctive Identity for Beauty Practitioners

      October 22, 2026

      A Practical Guide to Hormone Therapy Choices and Symptom Relief

      October 21, 2026

      Motion Sofa: Flexible Seating for Modern Living Spaces

      October 24, 2026

      How to Plan a Proposal Around Your Partner’s Style

      October 8, 2026

      Best Shampoo for Dandruff: Top Picks for a Healthy Scalp

      October 5, 2026

      Orient Watches Explained: Features, Functions and Design Details

      September 24, 2026

      How to Efficiently Manage Dual SIMs on One Phone for Frequent Business Travel

      October 22, 2026

      How to Find the Best Villas in Goa for Birthday Celebrations and Parties

      October 16, 2026

      Red Sea Days and Desert Nights in Hurghada

      October 7, 2026

      Luxury Crewed Yacht Charters in Greece: A Complete Guide to Private Yacht Holidays

      October 2, 2026

      How Pool Size and Depth Affect Water Chemistry Stability

      October 24, 2026

      Language Barriers While Traveling: What Actually Helps in Real-World Conversations?

      September 29, 2026

      How therapeutic techniques can vary from one practitioner to another

      September 29, 2026

      Turning Anger Into A Boundary Statement

      September 11, 2026

      Why Auckland Households Are Rethinking How They Move House These Days

      October 24, 2026

      What Should Auckland Businesses Look for Before Booking an Office Move?

      October 24, 2026

      What Should You Landscape First: The Front Yard or Backyard?

      October 24, 2026

      Strengthening Regulatory Compliance with an Identity Security Platform

      October 24, 2026
    • BUSINESS
      • OFFLINE BUSINESS
      • ONLINE BUSINESS
    • PROFILES
      • ENTREPRENEUR
      • HIGHEST PAID
      • RICHEST
      • WOMEN ENTREPRENEURS
    • Lifestyle
    CEOColumnCEOColumn
    Home»BLOGS»Will Your Insurance Rates Go Up If the Crash Was Not Your Fault?

    Will Your Insurance Rates Go Up If the Crash Was Not Your Fault?

    OliviaBy OliviaJuly 10, 2026Updated:July 31, 2026No Comments6 Mins Read

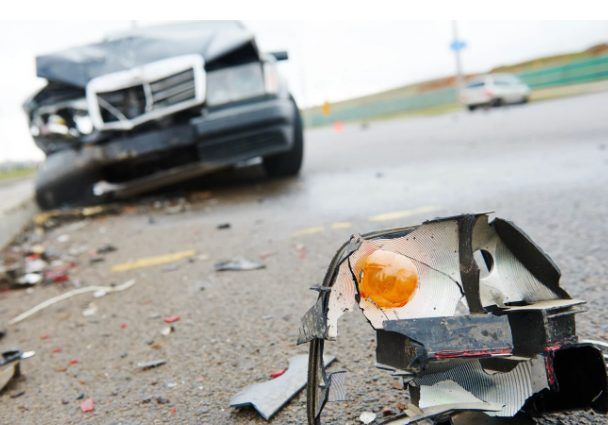
    A lot of people believe a crash always raises their insurance rates, even when they did nothing wrong. This fear stops some from filing a claim they deserve. It is time to bust this myth and look at the facts. The truth is more reassuring than the myth suggests.

    Knowing your rights as a consumer helps you make smart choices after a crash. A Houston auto accident attorney can help you understand them. Sutliff & Stout believes informed clients make stronger legal decisions, which is why the firm offers free legal resources alongside experienced representation. Their attorneys have recovered more than $1 billion in verdicts and settlements while fighting for clients in complex car, truck, and catastrophic injury cases throughout Texas.

    Below, we tackle the common myths about insurance rates and fault, and lay out what is actually true.

    Table of Contents

    Toggle
    • The myth, any crash raises your rates
    • The truth about fault and rates
    • Why you should still report a crash
    • What about my own coverage?
    • How to protect yourself
    • Shop around if your rates do change
    • The bottom line

    The myth, any crash raises your rates

    The myth is simple. Many people think that any crash, no matter who caused it, will raise their insurance rates. So they fear filing a claim even when another driver was clearly at fault. They worry that using their insurance will punish them.

    This fear is understandable but often misplaced. It leads people to skip claims they have every right to file. Some pay out of pocket for damage the other driver should cover. Others avoid getting the medical care they need. The myth causes real harm.

    The reality is more nuanced. Whether a crash affects your rates depends on the facts, especially fault. A not-at-fault crash is treated differently from an at-fault one. The blanket fear does not match how the system actually works.

    The truth about fault and rates

    Here is the key fact. Insurers generally treat at-fault and not-at-fault crashes differently. A driver who causes a crash is more likely to see a rate increase. A driver who was not at fault is in a better position.

    In many cases, a not-at-fault crash has less effect on your rates, or none, especially when the other driver’s insurance covers the damage. If the at-fault driver’s insurer pays, your own policy may not take the hit that an at-fault claim would.

    This is why fault matters so much, beyond just the claim itself. Establishing that the other driver caused the crash protects not only your recovery but potentially your rates. Clear proof of fault works in your favor on multiple fronts.

    Why you should still report a crash

    Some people, fearing a rate hike, avoid reporting a crash at all. This is usually a mistake. Reporting a crash and filing a valid claim is generally the right move, especially when you were not at fault.

    If you do not file, you may pay for damage and injuries that the other driver should cover. You could lose out on a recovery you are owed. The fear of a rate increase leads people to give up money and care they deserve. That trade rarely makes sense.

    There are also practical reasons to report. A police report and a timely claim create a record. If an injury surfaces later, or the other driver disputes the crash, that record protects you. Skipping the report to avoid a rate hike can leave you exposed.

    What about my own coverage?

    Even in a not-at-fault crash, you may use parts of your own coverage, and that is okay. For example, your uninsured or underinsured motorist coverage exists for crashes where the at-fault driver has no insurance or too little. Using it is the point of having it.

    This is coverage you paid for. Using it after a crash that was not your fault is exactly what it is designed for. You should not feel bad about using benefits you have been paying premiums to maintain. That is the purpose of insurance.

    The system is meant to protect you. When another driver causes a crash and cannot fully pay, your own coverage steps in. Using it in a not-at-fault crash is smart, not shameful. It is the safety net working as intended.

    How to protect yourself

    A few steps protect both your claim and your rates. First, establish fault clearly. Gather the crash report, photos, and witness contacts. The stronger the proof that the other driver was at fault, the better your position on every front.

    Second, report the crash and file a valid claim. Do not let fear of a rate hike stop you from recovering what you are owed. The value of a fair recovery usually far outweighs a possible small change in rates.

    Third, learn your rights. Free resources can teach you how fault, coverage, and rates actually interact. A firm that shares this information helps you make informed choices. Knowledge is the best defense against a myth that costs people money.

    Shop around if your rates do change

    Even if a not-at-fault crash does nudge your rates, you have options. Insurance is a competitive market. If your company raises your rates unfairly after a crash you did not cause, you can shop for a better deal elsewhere.

    Different insurers weigh crashes differently. One may raise rates after a not-at-fault crash while another does not. So a rate hike from one company is not the final word. You can compare quotes and switch. This competition is another reason not to fear filing a valid claim. The market gives you a way out if one insurer treats you unfairly.

    The bottom line

    Let us put the myth to rest. It is not true that any crash always raises your rates. Fault matters. A not-at-fault crash is treated differently, and often has less effect on your rates, especially when the other driver’s insurance covers the damage.

    Do not let the fear of a rate hike stop you from filing a claim you deserve. Establish fault, report the crash, and use the coverage you paid for. 

    Learn your rights from reliable, free resources. The facts are more reassuring than the myth. After a crash that was not your fault, pursuing a fair recovery is usually the smart and right thing to do.

    Share. Facebook Twitter Pinterest LinkedIn Tumblr Telegram Email
    Previous ArticleFahmaan Khan Height, Net Worth & Family 2026
    Next Article Choosing Your First Disposable Vape: A Beginner’s Guide
    Olivia

    Olivia is a contributing writer at CEOColumn.com, where she explores leadership strategies, business innovation, and entrepreneurial insights shaping today’s corporate world. With a background in business journalism and a passion for executive storytelling, Olivia delivers sharp, thought-provoking content that inspires CEOs, founders, and aspiring leaders alike. When she’s not writing, Olivia enjoys analyzing emerging business trends and mentoring young professionals in the startup ecosystem.

    Related Posts

    Why Auckland Households Are Rethinking How They Move House These Days

    October 24, 2026

    What Should Auckland Businesses Look for Before Booking an Office Move?

    October 24, 2026

    What Should You Landscape First: The Front Yard or Backyard?

    October 24, 2026
    Add A Comment
    Leave A Reply Cancel Reply

    You must be logged in to post a comment.

    Latest Posts

    How Pest Control In Meridian Solves Seasonal Insect Infestations

    October 25, 2026

    From Estimate to Payment: How Small Construction Firms Can Close the Cash Gap

    October 24, 2026

    Why Auckland Households Are Rethinking How They Move House These Days

    October 24, 2026

    What Should Auckland Businesses Look for Before Booking an Office Move?

    October 24, 2026

    What Should You Landscape First: The Front Yard or Backyard?

    October 24, 2026

    Motion Sofa: Flexible Seating for Modern Living Spaces

    October 24, 2026

    Sleepyhead 3 Seater Sofa Sizing: How to Be Sure It Fits Before You Order

    October 24, 2026

    7 Essential Network Security Practices Every Business Should Follow

    October 24, 2026

    How Pool Size and Depth Affect Water Chemistry Stability

    October 24, 2026

    Strengthening Regulatory Compliance with an Identity Security Platform

    October 24, 2026
    Recent Posts
    • How Pest Control In Meridian Solves Seasonal Insect Infestations October 25, 2026
    • From Estimate to Payment: How Small Construction Firms Can Close the Cash Gap October 24, 2026
    • Why Auckland Households Are Rethinking How They Move House These Days October 24, 2026
    • What Should Auckland Businesses Look for Before Booking an Office Move? October 24, 2026
    • What Should You Landscape First: The Front Yard or Backyard? October 24, 2026

    Your source for the serious news. CEO Column - We Talk Money, Business & Entrepreneurship. Visit our main page for more demos.

    We're social. Connect with us:
    |
    Email: Support@gposting.com

    Facebook X (Twitter) Instagram Pinterest LinkedIn WhatsApp
    Top Insights

    How Pest Control In Meridian Solves Seasonal Insect Infestations

    October 25, 2026

    From Estimate to Payment: How Small Construction Firms Can Close the Cash Gap

    October 24, 2026

    Why Auckland Households Are Rethinking How They Move House These Days

    October 24, 2026
    © Copyright 2025, All Rights Reserved
    • Home
    • Pricacy Policy
    • Contact Us

    Type above and press Enter to search. Press Esc to cancel.