
Growth should give your business more breathing room, not leave you scrambling to cover payroll. Financing can help you buy equipment, add capacity, or enter a new market, but the repayments need to fit the cash your business actually collects.
The goal is to fund expansion while keeping everyday operations steady. Start with your cash forecast, choose financing that suits the investment, and leave room for slower months.
Forecast Cash Flow Before You Borrow
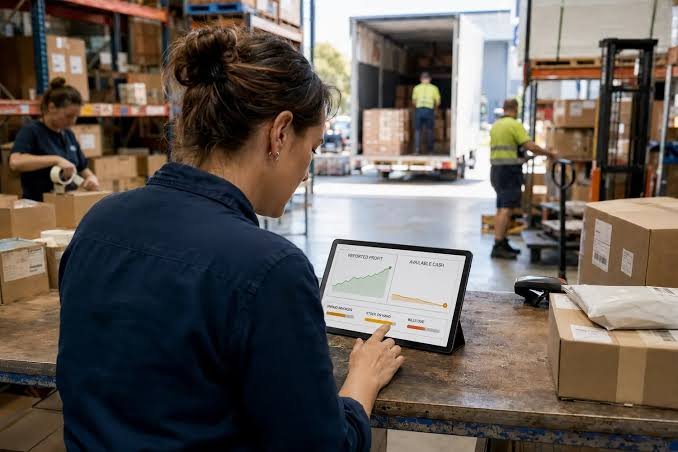
Build a cash flow forecast showing when money should arrive and when bills must be paid. Include payroll, rent, taxes, existing debt payments, and the costs of your proposed expansion.
According to the 2024 Small Business Credit Survey, 51% of surveyed employers reported uneven cash flow. If your receipts fluctuate, judge affordability against slower periods rather than your strongest sales month.
Separate confirmed orders from hopeful projections, and account for customers who pay late. A profitable contract will not cover next Friday’s payroll if payment arrives two months later.
Run a second forecast with delayed receipts and weaker sales. The difference helps reveal how much repayment pressure your business can realistically handle.
Match the Financing to Your Needs
Choose funding based on how the investment will generate cash. Equipment expected to serve the business for years has a different funding timeline from inventory purchased for a seasonal rush.
Term financing can spread a defined purchase across scheduled payments. A revolving credit line may better suit temporary gaps between paying suppliers and collecting customer receipts, provided you have a realistic repayment plan.
Avoid choosing an option solely by the advertised monthly payment. Compare fees, repayment frequency, total cost, and whether the agreement allows the flexibility your cash cycle needs.
Consider an SBA Loan
A substantial expansion may need financing that spreads costs over time rather than draining your operating account. An SBA-backed loan is, therefore, worth considering.
SBA loans can fund acquisitions, commercial real estate, and equipment, in addition to expansions. Plus, they come with flexible terms. So, they can help companies fund growth initiatives and manage cash flow.
If you go down this path, it could be useful to choose a lender in your local area. Local lender knowledge can be useful when discussing a project and its funding needs.
So, you could, for instance, apply for SBA loans for Houston businesses if your company is located in the vicinity.
Before you decide to use an SBA loan, make sure you know:
- What the loan amount will be
- Which fees affect the total borrowing cost
- How repayments would fit slower trading periods
Ask about collateral and any personal guarantee requirements, too. Understand those obligations before committing.
Release Cash From Everyday Operations
Before borrowing the full expansion budget, look for cash already tied up inside the business. Faster collections and better inventory control may reduce the amount you need to finance.
Send invoices promptly, make payment instructions clear, and follow up on overdue accounts consistently. Where appropriate, agree on deposits or milestone payments before starting work so you are not funding an entire customer project yourself.
Review slow-moving stock and purchases that can wait without disrupting service. Speak with suppliers about payment timing rather than assuming existing arrangements cannot change.
Keep expectations realistic when building your forecast. An unpaid invoice should not count as available cash until you have a reasonable basis for expecting collection, which takes us neatly to the next option…
Choose Invoice Factoring
If customer payment delays are holding back growth, consider invoice factoring. If you are not aware, it involves selling unpaid invoices to a provider in exchange for cash upfront, minus fees, rather than waiting for customers to pay.
Compare the full cost with the profit on the work before signing an agreement. Getting cash sooner should not leave you with too little margin to cover operating expenses.
Ask who will collect customer payments and what happens if an invoice goes unpaid. Review those terms carefully before deciding whether factoring fits your cash flow needs.
Use factoring selectively to cover a clear timing gap, such as buying materials for confirmed orders while earlier invoices remain unpaid. Build the fees into your cash flow forecast so faster access to cash does not quietly erode the profit funding your growth.
Keep Your Next Growth Step Manageable
Small business growth financing should support a workable plan. Not compensate for missing numbers.
Once financing is in place, compare actual receipts and payments with your forecast each month. Review any shortfall early, while you still have time to adjust spending or discuss concerns with your lender.
And before applying for financing, write down your project costs, repayment limits, and outstanding questions.
Has this article been helpful? If so, explore some of our other informative and interesting posts.
